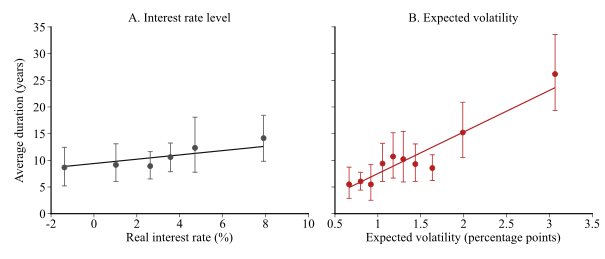
This paper characterizes the decision to exit sovereign defaults as a real options problem. Because the political costs of exiting default are irreversible, uncertainty about the future world interest rate makes it optimal for countries and creditors to wait before exercising the option to settle defaults.
Canadian Securities Institute Research Foundation PhD Award (2026)
Default duration increases with the level and, in particular, the expected volatility of the world interest rate at the start of default.
Working papers
Perpetual Futures and Basis Risk: Evidence from Cryptocurrency
With Will Gornall and Yizhou Xiao
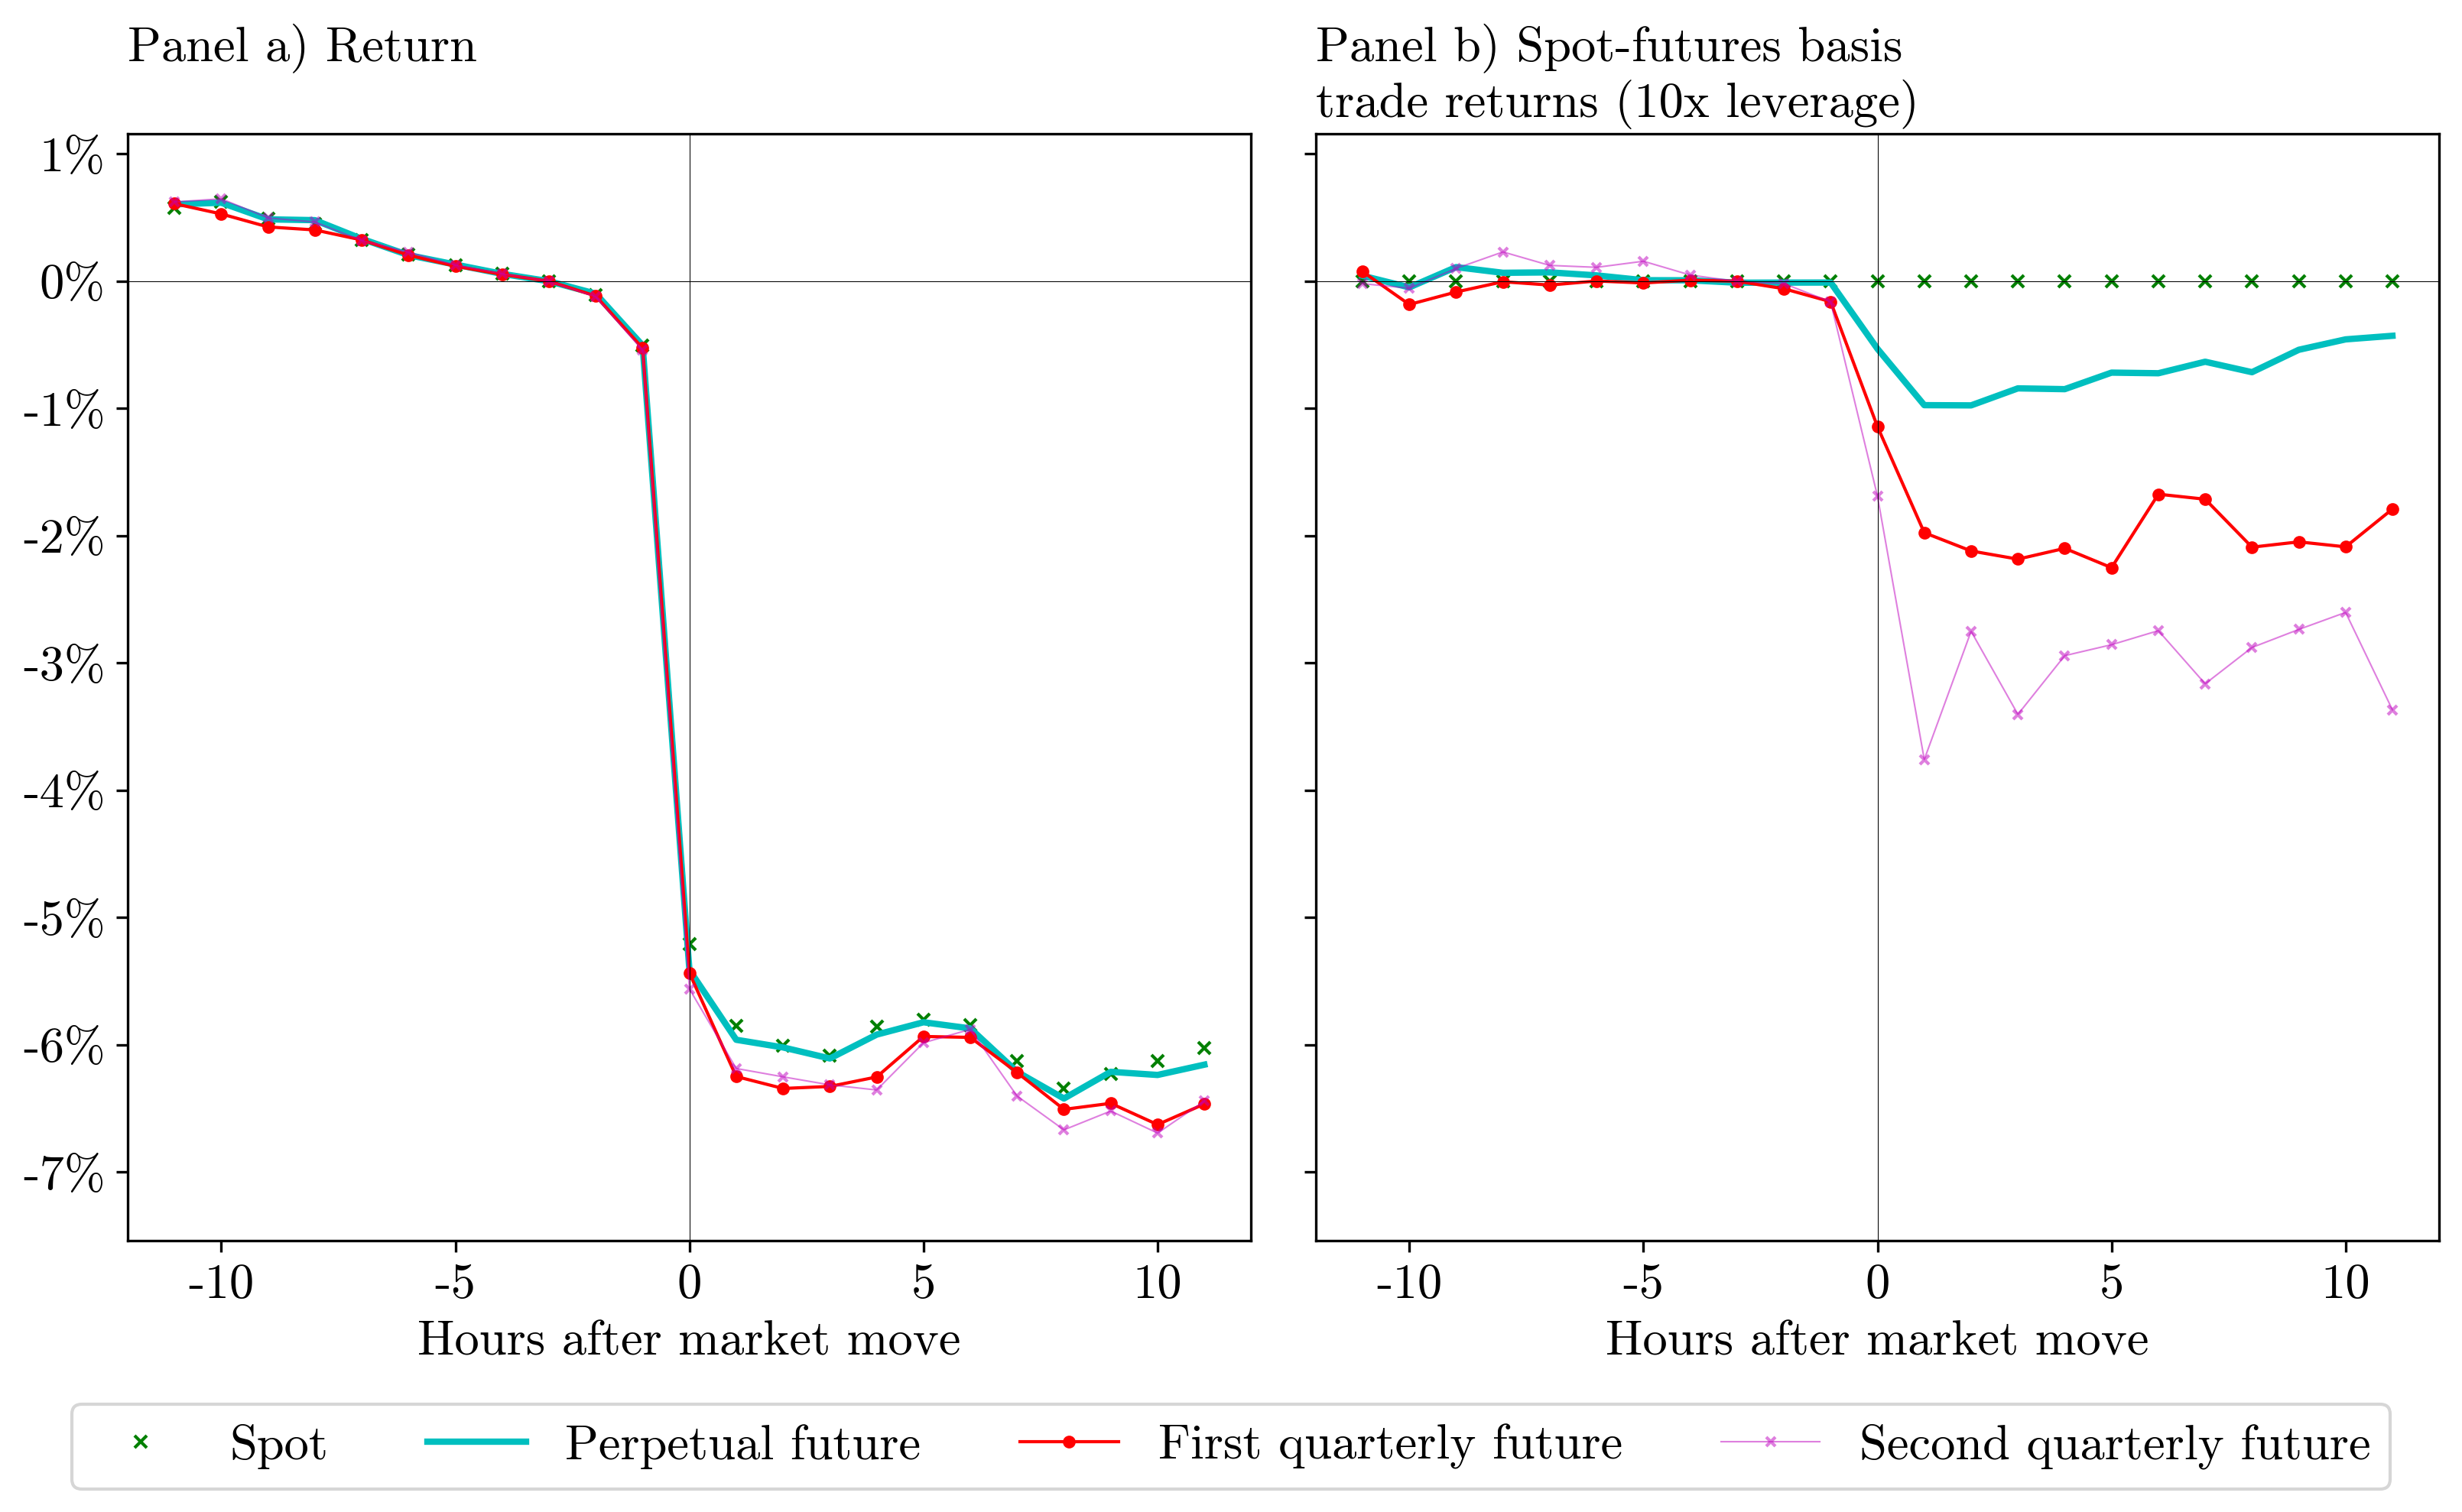
We study futures design when arbitrage capital is constrained. Perpetual futures use frequent funding payments to keep futures and spot prices aligned. In cryptocurrency markets, these contracts have tighter bases and smaller arbitrage losses during large price moves than quarterly futures.
Towards an (International) Political Theory of the Firm
Why do countries ever repay their debts? The literature emphasizes the roles of reputation (Eaton and Gersovitz, 1981) and sanctions (Bulow and Rogoff, 1989). Recent work has found that creditor lawsuits have become increasingly common and disrupt government access to international capital markets (Schumacher, Trebesch, and Enderlein, 2021). Extending Zingales (2017) to the international arena, I study how specialized global investors lobby in the United States to cut official financing to defaulting countries from multilateral organizations and bilateral donors. Without external financing, these countries turn to inflationary domestic financing, which erodes the political support of the incumbent government.
Partisanship and Regulatory Uncertainty
Partisanship among SEC commissioners reached a record high in the 2010s (Engelberg et al., 2023). Has this partisanship changed how markets perceive uncertainty about new or existing financial regulation? I isolate regulatory uncertainty using option prices around SEC votes on new rule proposals.
Research prior to the PhD
The Risk of External Financial Crisis
With Eduardo A. Cavallo and Eduardo Fernández-Arias · 2022
How does the external portfolio of nations affect the risk of external financial crises?