Asset pricing
Hedging Your Bets
Numerical examples and Python code for the Koijen and Yogo demand system approach to asset pricing.
Research data and open teaching materials.
Monthly series of the world real rate and its expected volatility over the last two centuries, built for my job market paper.
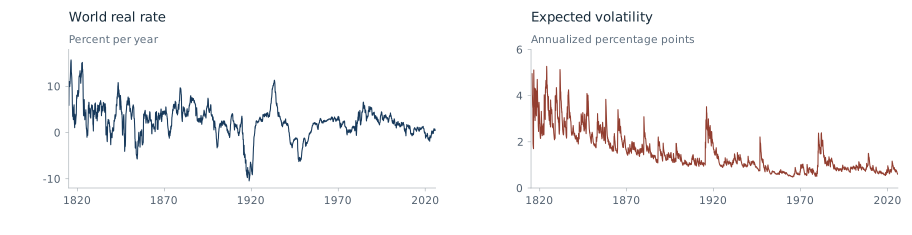
Building on Schmelzing (2020), the nominal world rate is the long maturity, default free yield of the world safe asset provider. As in Rogoff et al. (2024), expected inflation follows Homer and Sylla (1996). Expected volatility comes from the GARCH MIDAS model of Engle et al. (2013), fitted to the forecast errors of a second order autoregression for the world real rate.
Asset pricing
Numerical examples and Python code for the Koijen and Yogo demand system approach to asset pricing.
Portfolio choice
Python exercises on return prediction, tactical allocation, and portfolio construction.
International investments
A worked example of currency exposure and performance attribution for a portfolio of Canadian and American stocks.